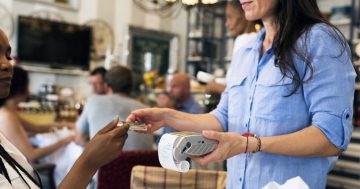

The RBA has directed that credit and debit card surcharges be abolished from 1 October. Photo: Michelle Kroll.
Hidden debit and credit card charges at the point of sale will soon be a thing of the past, following a high-level, independent review of the retail practice.
The Reserve Bank of Australia (RBA) has decided to implement a series of reforms that will include the abolition of surcharges billed on top of credit and debit card payments.
The decision comes after the publication last July of a consultation paper, and the completion by the RBA’s Payments System Board (PSB) of its Review of Merchant Card Payment Costs and Surcharging.
The PSB is responsible for determining the RBA’s payments system policy, particularly how it controls risk in the financial system, whether it promotes the efficiency of the payments system, and whether it promotes competition in the market for payment services.
It is also responsible for ensuring that the RBA exercises its powers under Parts 7.3 and 7.3B of the Corporations Act in a way that in the PSB’s opinion will best contribute to the overall stability of the financial system.
The 18-month review involved consultation with the payment sector, including the consideration of more than 250 written submissions and 150 meetings.
The PSB says the review benefited from engagement with a range of stakeholders with diverse views on the issues. It says careful consideration was given to these views in assessing which regulatory actions would best support the public interest, in line with the PSB’s responsibility to promote efficiency, competition and safety in the payments system.
The consultation paper found that surcharging is no longer achieving its intended purpose of steering consumers towards cheaper payment methods, because fewer people are using cash, while businesses are increasingly charging the same surcharge rate across debit and credit.
It also found that the interchange fees paid by businesses to card providers are too high, especially for small businesses, that more transparency is needed over card payment fees, and that it is too hard for businesses to shop around for better deals.
Australians typically pay between 0.5 and 3.5 per cent in transaction fees to use eftpos or credit cards, depending on the vendor, card or bank. While some businesses prefer to absorb these fees as a ‘’cost of doing business’’ or build them into their pricing, others add them on to the displayed or advertised price of an item, resulting an extra charge for the customer.
The changes will involve the removal of surcharging on debit, prepaid and credit cards on the designated eftpos, Mastercard and Visa card networks, making card payments simpler and more transparent, and increasing competition among payment service providers.
Despite claiming the changes will save consumers about $1.6 billion and businesses $200 million in surcharge fees annually, the paper says many of the surcharges previously displayed separately will now need to be built into the final cost.
The changes will also result in a lowering of the caps on interchange fees paid by businesses, which are expected to lower costs when accepting domestic or overseas card payments. It says small businesses should benefit the most because they tend to pay fees closer to the existing caps.
It also says increasing transparency over the fees charged by card networks and payment service providers will strengthen and enhance competition between players within the payments chain, will put downward pressure on card payment costs, and will make it easier for businesses to shop around for a better deal.
The removal of surcharging and reductions in the interchange caps are expected to come into force from 1 October, while the introduction of an interchange cap on foreign cards and some changes to payment cost transparency will come into effect from 1 April, 2027.
Despite largely supporting the changes to interchange regulations, the peak body representing small hospitality businesses has been actively advocating against the abolition of credit and debit card surcharges.
“Removing the ability for restaurants and cafes to levy reasonable, cost-based surcharges would not serve the public interest,” the Australian Restaurant & Cafe Association Ltd (ARCA) said in an August 2025 submission to the PSB.
“Instead, it would increase costs for small hospitality businesses, reduce transparency for consumers, and drive broad-based price increases.”
Shadow Treasurer Tim Wilson welcomed the changes, but called upon the Federal Government to ensure small businesses benefit from them.
“The Albanese Government must act to ensure that Australia’s struggling small businesses are not left picking up the bill compared to supermarkets with the end of merchant fees,” he said.
“Consumers will be happy with the RBA’s recommendation, but the cost will be picked up by small business. Merchant fee structures already favour scale to the large retailers, and small business shouldn’t lose out to supermarkets, who can absorb the cost.”
But Treasurer Jim Chalmers said the changes should prove more beneficial to small businesses.
“The current surcharge rules are difficult to follow and customers are often slugged with surprise surcharges at the checkout, in‑store, online or at the cafe or pub,” he said.
“Small businesses will no longer have to wade through complex surcharging rules and will be armed with more information so they can shop around for card payment services that meet their needs.
“The Australian Small Business and Family Enterprise Ombudsman will help small businesses understand changes and ensure they are well positioned to benefit from the reduction in costs.”
Original Article published by Andrew McLaughlin on PS News.